Strategic communication engine · Refi & HELOC
Load the title export you already buy. The engine amortizes every note against its own terms, ranks who is worth calling today, and writes refi and HELOC outreach carrying that borrower's real figures — with your licensing footer on every piece.
14 days free · no card · built by a licensed originator, NMLS #1530065
Bring your own list
Reads any title export — TitlePro, DataTree, PropertyRadar, or the spreadsheet your title rep sends. CSV, Excel, whatever they gave you.
Works with your lender today
Outputs MISMO 3.4. ARIVE, Encompass, LendingPad and Byte import it directly. No integration to buy, no API key, no partnership.
Built by a licensed originator
Written by a working MLO for his own production, not by a software company guessing at the workflow. NMLS #1530065.
Live generation
Left, what the engine does with one row of a title export. Right, what the borrower receives. Every figure on the card is derived from that borrower's own note, not from an average.
refinance opportunity · jordan taylor
$283 / month
Annual
$3,396
Money Saved
$135,923
Break-even
42 mo.
Rate
7.20→5.85
“Hi Jordan — I ran your note against today's wholesale pricing and found a real, documented reduction. Here is the full analysis…”
Generator anatomy
Nothing is a template with the name swapped — each sentence is derived from that borrower's file.
Compare to live HELOC wholesale pricing, those indices compared against the borrower's rate, the origination start date, their real terms. A result they can verify on their statement.
Why it chose this
Rate 7.20% → 5.85% pulled from the note, not an average.
Equity position, tenure and property profile shape the framing: a cash-out for a growing family reads nothing like a term reduction for an owner five years from payoff.
Why it chose this
“…without extending the years you have already paid.”
Your name, NMLS, brokerage, state licensing and an opt-out are written into every piece, and estimate language is enforced. No wording is left to chance and nothing sends itself.
Why it chose this
NMLS #1530065 · Equal Housing Opportunity · opt-out included.
How it works
Each step produces the input for the next one, and the last step produces a file.
Step one
Drop in the title export you already buy. Every property is amortized against its own note — the real rate, the real start date, the real term — and sorted into refinance, equity and second-lien candidates. The ones who do not qualify are told to you plainly instead of padding a count.
Refinance snapshot
Kevyn Smith
1234 Desert Palm Dr, Palm Desert, CA
Est. monthly savings
$394/mo.
Refinance snapshot
Dana Whitfield
88 Mission St, Pasadena, CA
Est. monthly savings
$313/mo.
Refinance snapshot
Priya Raman
77 Cedar Ct, San Jose, CA
Est. monthly savings
−$1,283/mo.
The third borrower holds a rate worth keeping — the engine says so in red rather than padding a count.
Step two
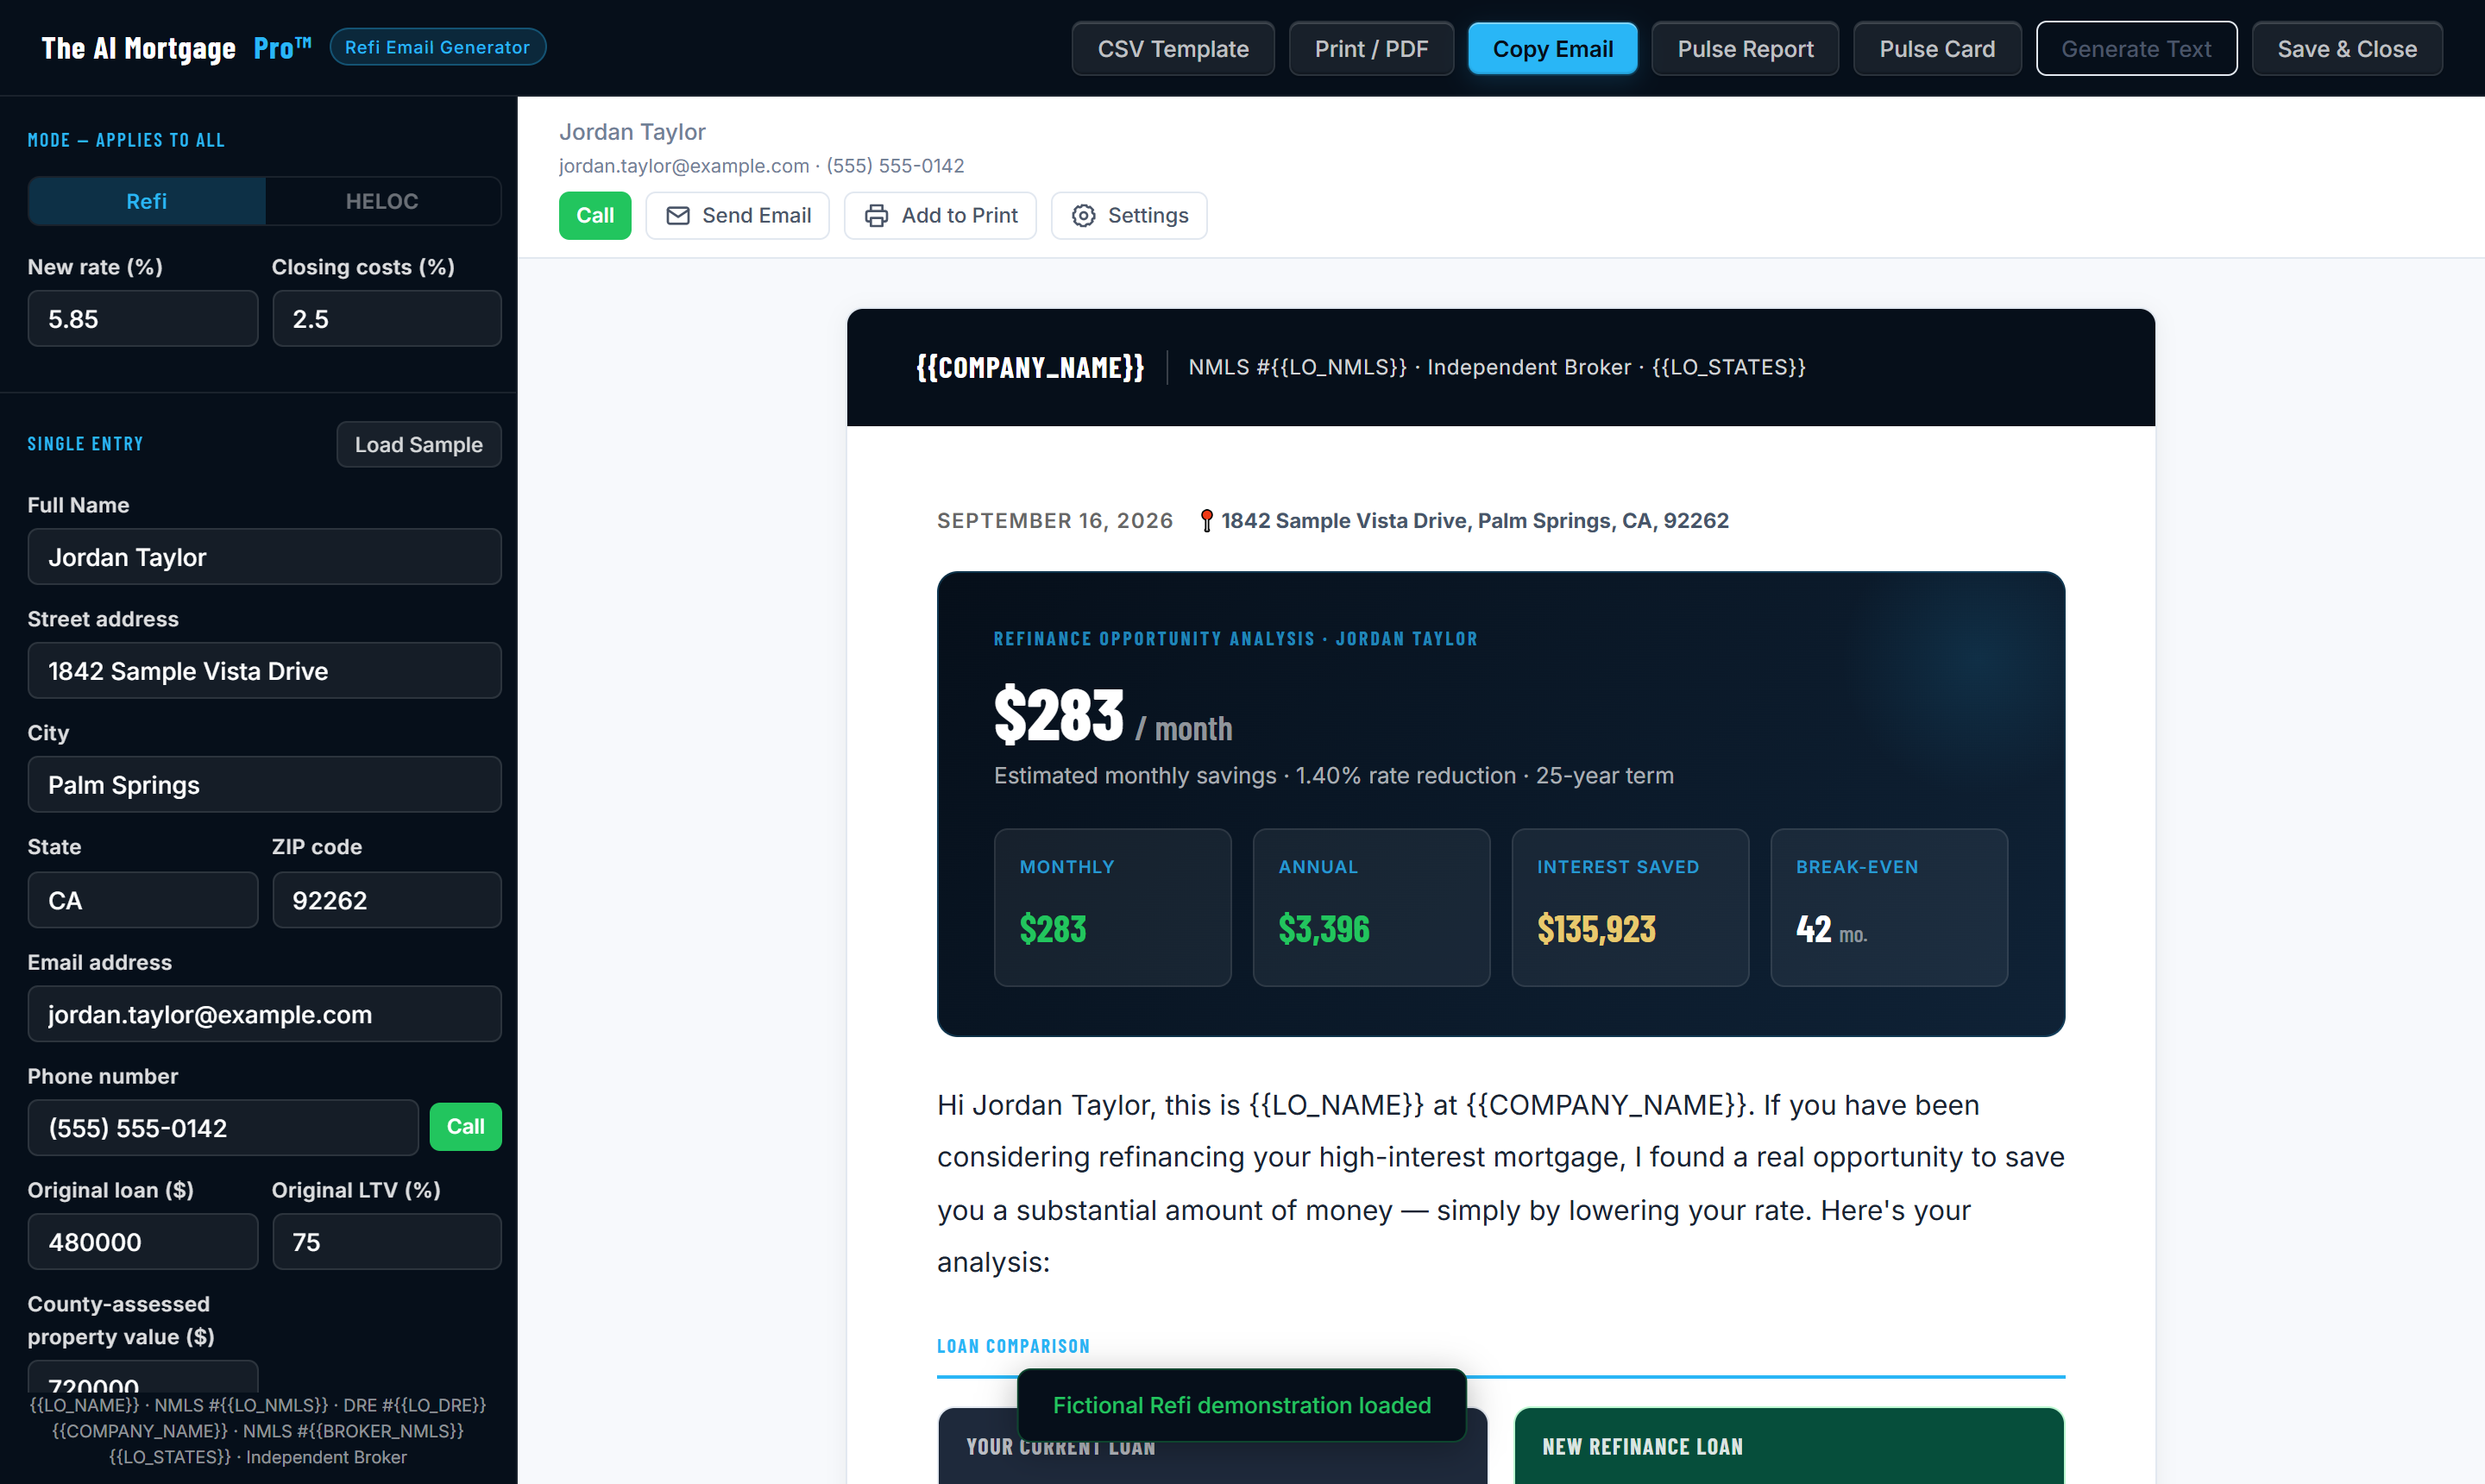
Email, card, letter, print summary or postcard batch — each one carrying that borrower's own figures and the full licensing footer, every time, with no wording left to chance. Nothing sends itself. You decide who gets touched and when.
Step three
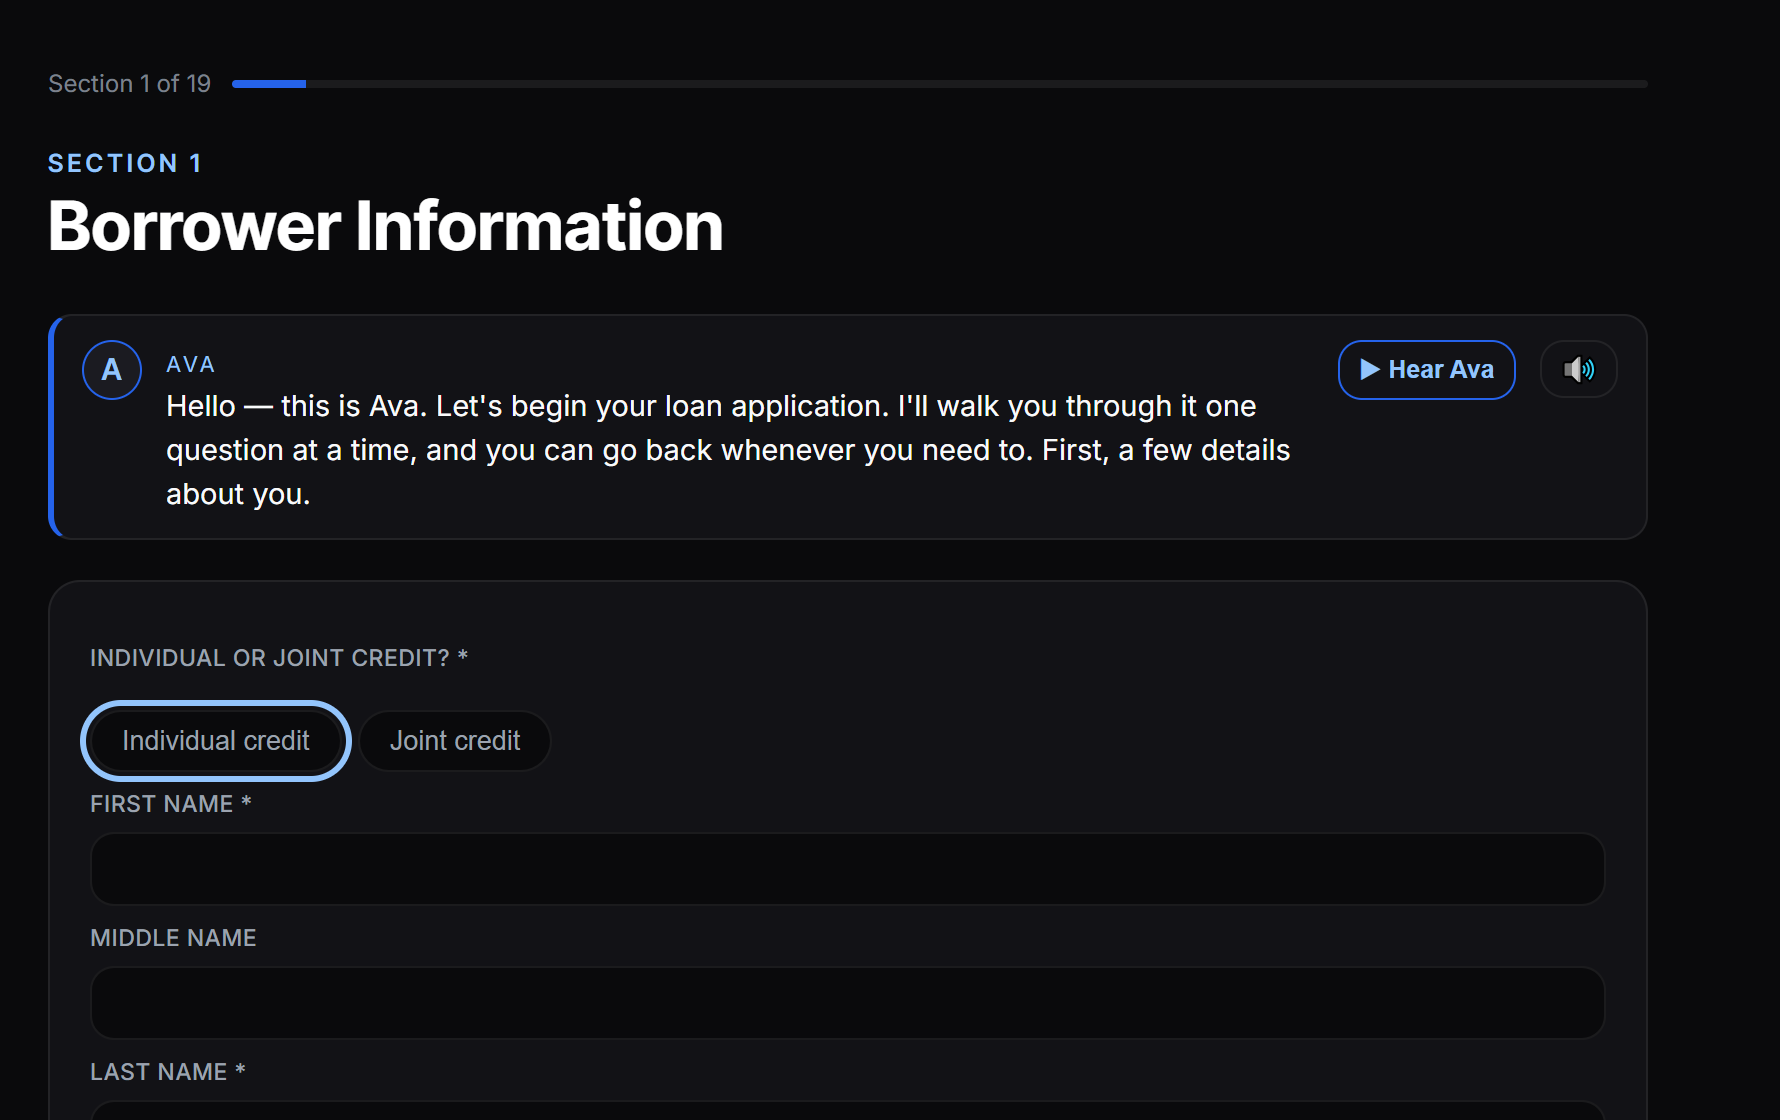
When they respond, they are not handed a PDF or pushed into somebody else's portal. Ava walks them through all nineteen sections of the 1003 one question at a time, out loud if they prefer, and will not let a required answer go missing.
Step four
A completed 1003 and a schema-valid MISMO 3.4 file, with the originator, the NMLS and every declaration in place. Upload it to your lender and the loan is in their system. That is where everyone else stops short.
<TERMS_OF_LOAN>
  <BaseLoanAmount>380000</BaseLoanAmount>
  <LienPriorityType>FirstLien</LienPriorityType>
  <LoanPurposeType>Refinance</LoanPurposeType>
  <MortgageType>Conventional</MortgageType>
  <NoteAmount>380000</NoteAmount>
</TERMS_OF_LOAN>
Real output. Schema-valid against the MISMO 3.4 reference model.
The borrower-facing funnel
The generator does not send borrowers to a dead inbox. Each refi and HELOC piece points at a live consumer funnel — break-even calculator, plain-language program breakdown, and a five-minute application that hands you the 1003. See the exact funnel running in production at ai.myeshloans.com/refi.
Lower rate, payment or term with no cash out. Flagged when the borrower's note sits 0.5%+ above today's pricing.
No cash out
Converts built equity into capital for renovations, debt consolidation or the next investment property.
Equity released
Keeps a low first mortgage in place and prices the second against current indices instead of resetting the clock.
First mortgage untouched
Live funnel · break-even engine
Monthly savings
+$159
Break-even
4.2 yrs
Closing costs
$7,866
Net over stay
+$1,674
Consumer-side figures, generated from the same amortization engine that ranks your farm — so the number on the card is the number on the funnel.
View the live refi funnel ↗
Why this is different
The application is where borrowers quit. Every competing platform hands them to your origination system at exactly that moment and calls it an integration.
An AI mortgage CRM
The AI Mortgage Pro
Efficiency calculator
Move the slider to the size of the farm or database you can reach today.
Records in your database
2,500
Projected output
Qualified refi & HELOC candidates
150
Potential unlocked equity
$16.5M
Hours saved per week
6
An illustration, not a measured result. It assumes 6% of a list qualifies, $110,000 of average unlocked equity per qualifying borrower, and 9 minutes of manual analysis and writing each. Your own farm will differ — running it is how you find out.
Carry these numbers into my request
Reconciliation
| Note rate | 7.200% |
|---|---|
| Originated | 06/2023 |
| Term | 360 mo. |
| Servicer says | $674,686 |
| Engine says | $674,686 , which matches |
Demonstration figures. Every number that reaches a real borrower is reconciled exactly this way, against that borrower's own note.
R. Sumlin · NMLS #1530065
Verify at NMLS Consumer Access ↗
Who built it
I built this for my own book of business because nothing on the market would do it. It reads the same title data I buy, works the same lenders I work, and produces the file I submit. Every calculation in it has been checked against a real note and a real mortgage statement, because I am the one who has to answer for the number on the card.
Originator
Robert Sumlin
NMLS
#1530065
Licensed
California & Texas
Pricing
The funded competition charges two hundred a month and another two hundred and ninety-nine before you have sent a single piece.
Starting at$49 / month
Free for fourteen days. No card to start. Cancel from the settings screen.
Start your fourteen days
Straight answers
No, and you cannot. You bring the title export you already buy or receive from your title representative. If you do not have one, there is a short guide to getting a farm from a title company in your county, usually at no cost to a licensed originator.
If your lender accepts MISMO 3.4, and effectively all of them do, it works today. ARIVE imports these files directly, twenty at a time. So do Encompass, LendingPad and Byte. There is no integration to purchase and no partnership required.
No. This is not a CRM and does not try to be one. It finds the borrower and takes the application. Your contact database keeps doing what it does, and every list here exports to a spreadsheet it can read.
Never. Nothing leaves without you pressing the button. Every written piece carries your full licensing footer and an opt-out, and the compliance responsibility stays where your license already puts it.
Not to use this. You take the application here and submit the file to your lender. If you shop a dozen wholesalers and need a pricing engine, keep the one you have.
Applications are yours, visible only to you, and are removed from the server once you have downloaded the file. Nothing is sold, nothing is shared, and no other user of this platform can see your pipeline.
The founding cohort
You run your own list
Load the title export you already buy on day one. No sample data, no sandbox, no demonstration account. If it does not find loans in your farm, you will know inside an hour.
Every format, no cap
Unlimited analysis and every outreach format, including the full application and the MISMO file. Nothing is metered.
Your list stays yours
Your borrowers are visible only to you, nothing is sold or shared, and applications come off the server once you have downloaded the file.
You talk to the person who built it
Founding seats are limited on purpose. You are dealing directly with a licensed originator, not a support queue.
Request a seat
I read these myself. You will hear back from me, usually the same day, and setup takes about ten minutes on a call.
14 days free · no card · your list and your borrowers stay yours.
Already have access? Sign in to the generator ↗